Property damage can leave you with a building you cannot fully use and an insurance company questioning what it owes. When the insurer delays, denies, or undervalues a covered loss, our Kentucky property damage lawyers can review your policy, document the disputed damage, and press for the benefits the contract provides.
At Denham Property & Injury Law Firm, we represent policyholders in residential and commercial insurance disputes throughout Kentucky. From our Lexington office, we focus on the policy language, carrier conduct, and property evidence that shape these cases.
If your claim has stalled or the numbers do not add up, call (859) 900-BART (2278) or contact us online for a free consultation with our Kentucky insurance claim attorneys.
When Should I Call a Kentucky Property Damage Lawyer?
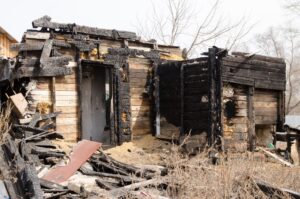
A Kentucky property damage lawyer may help when an insurer disputes coverage, delays a decision, pays less than the documented repair cost, or interprets the policy in a way that leaves a major loss unpaid. Legal help can also be valuable before a disagreement hardens into a denial.
Common warning signs include:
- The insurer keeps requesting information without resolving the claim.
- The adjuster’s estimate omits damaged areas or uses a narrower repair scope.
- The carrier applies depreciation or deductibles you did not expect.
- The insurer attributes storm damage to wear, maintenance, or another exclusion.
- A business claim leaves out covered income losses or extra expenses.
- The carrier denies coverage without clearly connecting its decision to the policy.
We compare the insurer’s position with the policy, loss evidence, estimates, and Kentucky claim-handling rules to identify what remains disputed and what the carrier must justify.
| Claim problem | What legal review can address |
|---|---|
| Denied claim | Policy language, exclusions, causation, and the stated basis for denial |
| Underpaid estimate | Repair scope, pricing, depreciation, matching, and omitted damage |
| Delayed claim | Carrier communications, investigation history, and Kentucky timing rules |
| Roof dispute | Wind or hail damage, matching, repair scope, deductibles, and valuation |
| Commercial loss | Building damage, contents, business income, and extra-expense provisions |
What Types of Kentucky Property Damage Claims Do We Handle?
Our property insurance practice covers losses where a policyholder and carrier disagree about covered damage or payment. The exact coverage depends on the policy, cause of loss, endorsements, deductibles, limits, and exclusions.
Hail Damage Claims
Hail can damage roofing, siding, gutters, windows, and other exterior surfaces. Disputes often center on whether hail caused new physical damage, whether a spot repair is sufficient, and whether replacement materials can reasonably match under Kentucky’s claim-settlement rules. Understanding these issues is important when filing a hail damage insurance claim and seeking coverage for the full extent of storm-related damage.
Wind Damage Claims
High winds can lift shingles, damage siding, break windows, and create openings that allow rain inside. Properly documenting wind damage for insurance claims helps establish the extent of the storm’s impact. We review wind damage insurance claims by separating new storm damage from wear, testing the insurer’s repair scope, and determining whether resulting interior damage falls within the policy.
Tornado Damage Claims
Tornadoes can combine wind, debris impact, fallen trees, structural damage, and rain intrusion in one loss. Preparing for tornado damage claims involves understanding the types of damage that may be covered and gathering evidence to support the loss. These claims may also involve temporary housing, debris removal, code upgrades, and disputes over whether the insurer’s estimate captures the full covered damage.
Fire and Smoke Damage Claims
Fire losses can extend well beyond burned materials. Smoke, soot, firefighting water, damaged contents, debris removal, and temporary relocation may each involve separate coverage and valuation questions. Understanding insurance coverage for fire damage helps policyholders assess which losses may be covered. We compare the carrier’s scope with the policy and the evidence showing what must be cleaned, repaired, or replaced.
Water Damage Claims
Burst pipes, appliance failures, plumbing leaks, and other water events can damage walls, flooring, cabinets, contents, and other parts of a building. Coverage often depends on the source and timing of the water, including whether the insurer alleges seepage, deterioration, or another exclusion.
Flood Damage Claims
Flooding is usually treated differently from water released inside a building. A standard property policy may exclude rising or surface water, while separate flood coverage can apply. When several sources of water are involved, we examine the sequence of events instead of treating every form of water intrusion as flooding.
Commercial Property Damage Claims
Business losses may involve building repairs, inventory, equipment, business income, extra expense, tenant improvements, or other covered losses. We review commercial property damage insurance claims against the actual coverage form, endorsements, limits, deductibles, and carrier calculations so the dispute stays tied to the policy the business purchased.
What Kentucky Rules Apply When an Insurer Handles a Property Claim?
Kentucky law sets standards for how insurers investigate, communicate, and resolve property claims. These rules do not guarantee coverage or a particular payment, but they create requirements that carriers must follow while evaluating a claim.
| Kentucky rule | What it means for a property claim |
|---|---|
| KRS 304.12-230 | Bars specified unfair settlement practices, including certain investigation and explanation failures |
| KRS 304.12-235 | Addresses payment timing after required notice and proof, with consequences in qualifying cases |
| 806 KAR 12:095 | Adds standards for communications, investigations, payment, replacement cost, and matching |
KRS 304.12-230 identifies unfair claim settlement practices such as refusing to pay without a reasonable investigation and failing to provide a reasonable explanation for a denial or compromise offer.
KRS 304.12-235 generally addresses payment within 30 days after the insurer receives the notice and proof of claim required by the policy. Disputed claims can involve additional questions, including whether the carrier had a reasonable foundation for delay.
A simple disagreement over value does not automatically establish bad faith. When the facts support a broader carrier-conduct issue, we also evaluate when your insurer acts in bad faith under Kentucky law and what remedies may apply.
If the carrier’s explanation does not match the policy or the damage you are seeing, we can review the claim before the dispute grows more expensive. Call (859) 900-BART (2278) for a free consultation about the insurer’s current position.
How Are Roof Damage and Matching Disputes Evaluated?
Roof claims require a close comparison of the physical damage, repair scope, policy terms, and Kentucky settlement rules. An insurer may agree that some shingles or pieces of siding need replacement yet dispute how much of the roof or surrounding area it must repair or replace.
We look at several issues that commonly affect the amount owed:
- Whether wind or hail caused direct physical damage.
- Whether the carrier attributes part of the condition to age or wear.
- Whether replacement materials reasonably match the existing roof or exterior.
- Whether the estimate includes necessary work connected to a covered repair.
- Whether the policy pays replacement cost or actual cash value at a particular stage.
- Whether a separate wind or hail deductible applies.
The Kentucky Department of Insurance’s wind and hail guidance also explains that policies may use percentage deductibles and may value roofs on either a replacement-cost or depreciated basis. The policy controls the actual claim, so we review its language rather than relying on a general assumption.
How Do Kentucky Commercial Property Claims Differ From Homeowner Claims?
Commercial property claims often involve more layers of coverage than residential claims. A physical loss may interrupt operations, damage inventory, affect leased space, or create added costs during repairs.
A business policy may include coverage for:
- Building repairs or replacement.
- Business personal property and inventory.
- Equipment and machinery.
- Business income losses.
- Extra expenses tied to continued operations.
- Debris removal or code-related costs, when covered.
Not every policy includes each category, and limits or waiting periods may apply. Our work starts with the actual contract and the carrier’s claim file so we can identify which disputed losses fall within the purchased coverage.
Where Are Kentucky Property Damage Disputes Handled?
Kentucky property insurance disputes may remain in the claim process, enter appraisal or another policy-based procedure, or proceed to litigation. The proper forum depends on the policy, parties, location, legal claims, and jurisdictional requirements.
For Lexington-area matters, litigation may proceed in Fayette Circuit Court or, when federal jurisdiction exists, the U.S. District Court for the Eastern District of Kentucky. Louisville-area disputes may be heard in the Jefferson Circuit Court or the U.S. District Court for the Western District of Kentucky.
A Louisville property damage lawyer or statewide counsel should evaluate venue based on the actual dispute rather than assume one court applies to every Kentucky claim.
Why Choose Denham Property & Injury Law Firm for a Kentucky Property Claim?
We focus our practice on policyholder-side insurance disputes, so the carrier’s interpretation of policies and claim handling are central to our work. J. Bart Denham, Esq., our founder and principal attorney, earned both his business degree and law degree from the University of Kentucky and built his legal career around litigation and insurance-related property losses.
Bart’s background includes in-house legal work and property-loss litigation before founding the firm. That combination helps us examine a claim from both the contract and business sides, especially when repair costs, valuation, lost income, or carrier communications overlap.
We believe the highest measure of our success comes not just from our case results but from the words of our clients who’ve told us about their experience.
“Bart and his team guided us through every step of our insurance claim. Their communication, empathy, and dedication made a stressful process feel manageable.”, Theresa M.
If you want a Kentucky property damage attorney to review what the insurer has done so far, call (859) 900-BART (2278). Our Kentucky headquarters is at 250 W Main St., Ste. 2650, Lexington, KY 40507.
Questions Kentucky Property Owners Ask Before Hiring a Lawyer
Can a lawyer take over communications with my property insurance company?
Yes, once we represent you, we can handle appropriate claim communications with the insurer and its representatives. That can reduce mixed messages and keep requests, coverage positions, and settlement discussions organized while we evaluate the legal and factual issues in your claim.
Can I hire a lawyer if the insurance company already sent a partial payment?
Yes, a partial payment does not necessarily end a property claim. We can review what the payment covered, whether the insurer left other covered amounts unresolved, and whether any release or settlement language affects your options before determining what can still be pursued.
What if my insurance check includes my mortgage company?
A mortgage company may appear on a property insurance payment because the lender has a financial interest in the insured property. We can explain how that affects the claim and coordinate the legal side of a payment dispute, but the specific process depends on the mortgage and insurance documents.
Does an appraisal clause mean I cannot hire a lawyer?
No, an appraisal clause does not necessarily prevent you from hiring a lawyer. Appraisal usually addresses the amount of a covered loss rather than every coverage or legal dispute. We can review whether appraisal applies, what issues remain outside appraisal, and how the policy frames the process.
How much does it cost to speak with Denham Property & Injury Law Firm?
We offer a free consultation for Kentucky property insurance matters we handle. During that conversation, we can review the basic claim history, identify the primary coverage or payment dispute, and explain whether our firm can assist.
Can you help if my property is in Louisville but your Kentucky office is in Lexington?
Yes, our Lexington headquarters serves policyholders across Kentucky, including Louisville and surrounding communities. The property’s location can affect venue and local litigation details, but it does not limit our ability to evaluate a qualifying Kentucky insurance dispute.
How soon should I contact a lawyer after a property claim dispute starts?
It is often useful to contact a lawyer as soon as the insurer has delayed, denied, or materially underpaid the claim. Insurance policies can impose notice, proof-of-loss, suit-limitation, and other deadlines, so early legal review can identify time-sensitive requirements before they become another dispute.
Talk With a Kentucky Property Damage Lawyer About Your Claim

A property insurance dispute can become expensive quickly when repairs remain unfinished or a business cannot return to normal operations. You do not have to accept the carrier’s estimate or denial without having the policy and claim handling reviewed.
Denham Property & Injury Law Firm represents Kentucky policyholders in denied, delayed, and underpaid property claims. Call (859) 900-BART (2278) or request a free consultation online. You can also visit our Lexington office at 250 W Main St., Ste. 2650, Lexington, KY 40507.